


-
 Spagna
Indennità di clientela in Spagna: i limiti della rinuncia
15 Novembre 2026
- Contenzioso
- Distribuzione
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
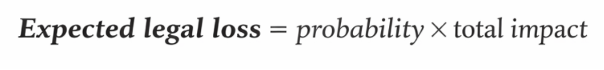
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
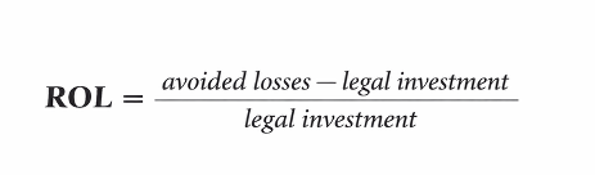
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
 Francia
 Cina
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
 Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Angel
The Contract Covers the Dispute. But Who Explains It?
25 Agosto 2026
-
 Canada
- Compliance
- Contratti
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Larry
Ceo fraud in Portugal: how to react fast, recover funds and strengthen payment security
4 Giugno 2026
-
 Portogallo
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Carolina
Spain | Franchising, Theory Of Risk and Guarantees By Franchisee
15 Maggio 2026
-
Spagna
- Distribuzione
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Javier
Crisis Management for Law Firms
26 Febbraio 2026
-
Canada
- Compliance
- Contenzioso
- Diritto penale d’impresa
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Larry
Managing Lawsuit Risk: A Budgeting Framework for Legal Costs
19 Febbraio 2026
-
 Italia
- Contratti
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Roberto
I Pericoli e i Costi del Contenzioso negli Stati Uniti d’America
3 Gennaio 2026
-
 USA
- Arbitrato
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Roberto
The lawyer-coach: a new way of practising
23 Dicembre 2025
-
Spagna
- Mediazione
- Contratti
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
Scrivi a Ignacio
Spain – Man in the Middle fraud and EU Regulation 2024/886: a paradigm shift
3 Novembre 2025
-
Spagna
- Bancario
- Titoli e strumenti finanziari
- Contenzioso
In Spagna la rinuncia all’indennità di clientela contenuta in un contratto di distribuzione non protegge sempre il produttore. L’Audiencia Provincial di Barcellona (la Corte d’Appello) ha condannato un produttore a pagare al distributore oltre 100.000 euro a titolo di indennità di clientela e di risarcimento per insufficiente preavviso, nonostante la rinuncia scritta, perché ha ritenuto che il contratto fosse scaduto e che la buona fede ne limitasse gli effetti. Per evitare lo stesso rischio, il produttore deve rinnovare il contratto per iscritto prima della scadenza o prevedere espressamente che le rinunce restino efficaci, precisare la clientela coperta e concedere un preavviso proporzionato alla durata del rapporto.
Di cosa parliamo in questo articolo
- Il caso del distributore e la condanna del produttore
- Cosa ha deciso la Corte sulla rinuncia
- Perché la rinuncia non è stata applicata
- Rinuncia valida, ma con limiti: distribuzione e agenzia
- Se la rinuncia dovesse cadere con il contratto
- Cosa devono fare i produttori che distribuiscono in Spagna
Indennità di clientela in Spagna: il caso del distributore
Per oltre vent’anni, produttore e distributore hanno lavorato insieme senza un contratto scritto. Nel 2018 ne hanno firmato uno della durata di due anni. Il distributore ha accettato di rinunciare sia all’indennità di clientela sia al risarcimento dei danni derivanti dalla cessazione del rapporto.
Il contratto è scaduto nel dicembre 2020. Nessuna delle parti lo ha rinnovato, ma entrambe hanno continuato a lavorare insieme.
Alcuni mesi dopo, il produttore ha deciso di porre fine al rapporto. Ha concesso un preavviso inferiore a due mesi e contestato al distributore inadempimenti che non è riuscito a dimostrare.
Rinuncia all’indennità di clientela: cosa ha deciso la Corte
Nella distribuzione, il distributore può rinunciare all’indennità di clientela, mentre nell’agenzia la rinuncia anticipata non è consentita. In questo caso, tuttavia, la Corte ha ritenuto che la rinuncia non fosse più applicabile, perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. Ha inoltre ritenuto che la buona fede potesse limitarne gli effetti, considerata la durata del rapporto e la sua cessazione senza giusta causa.
L’argomento fondato sulla scadenza è discutibile: una clausola destinata a disciplinare la fine del contratto non dovrebbe perdere efficacia semplicemente perché il contratto termina. Per evitare questa incertezza, se le parti continuano a lavorare dopo la scadenza, è opportuno rinnovare il contratto per iscritto oppure stabilire espressamente che le rinunce mantengono i propri effetti.
Perché la rinuncia non è stata applicata?
La Corte ha fondato la propria decisione su due ragioni.
La prima era la scadenza del contratto. Poiché le parti avevano continuato a lavorare senza firmare un nuovo documento, la Corte ha ritenuto che la rinuncia non fosse più efficace quando il produttore ha posto fine al rapporto.
La seconda era la buona fede. Anche se la rinuncia fosse rimasta applicabile, secondo la Corte non avrebbe potuto produrre pienamente i suoi effetti in quelle circostanze: oltre venticinque anni di collaborazione, una clientela sviluppata dal distributore e una cessazione senza giusta causa.
Rinuncia all’indennità di clientela: valida, ma con limiti
La condanna sorprende perché il distributore può, in linea di principio, rinunciare a questa indennità. Per comprenderne il motivo, occorre distinguere la distribuzione dall’agenzia.
Nell’agenzia, la legge tutela l’agente contro una rinuncia anticipata. Lo prevede l’articolo 3 della legge spagnola 12/1992 sul contratto di agenzia, in relazione all’indennità di clientela disciplinata dall’articolo 28.
Nella distribuzione, il Tribunal Supremo applica per analogia l’articolo 28 quando ne ricorrono i presupposti (sentenza 944/2023 del 13 giugno). Ciò non impedisce, però, che produttore e distributore concordino di escludere ogni indennizzo in caso di recesso con preavviso. Il Tribunal Supremo lo ha affermato nelle sentenze del 4 dicembre 2007, del 15 gennaio 2008, pronunciata in composizione plenaria, e del 25 aprile 2011.
La distinzione riguarda il modo in cui il rapporto termina. Questo orientamento si riferisce alla cessazione ordinaria, con preavviso o per scadenza del termine. La rinuncia offre meno certezze quando il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente, come è accaduto in questo caso.
La rinuncia doveva perdere efficacia con il contratto?
Tra le due ragioni indicate dalla Corte, la più discutibile è la prima: che la rinuncia non fosse più applicabile perché il contratto era scaduto.
Il Tribunal Supremo ha applicato clausole di esclusione proprio dopo la scadenza di un contratto. È accaduto nella sentenza del 23 dicembre 2008. In quel caso, il contratto di un concessionario era terminato alla scadenza della proroga. La Corte ha negato l’indennità di clientela perché il contratto stesso escludeva qualsiasi pretesa legata alla sua cessazione.
La questione è semplice: se una clausola viene pattuita per disciplinare ciò che accadrà alla fine del contratto, è difficile sostenere che perda efficacia per il solo fatto che il contratto termini.
Qui c’è una differenza: le parti hanno continuato a lavorare dopo la scadenza e, secondo la Corte, lo hanno fatto alle condizioni tradizionali del rapporto. Ma la prosecuzione dell’attività non dimostra, da sola, che volessero eliminare una rinuncia riferita alla clientela sviluppata fino a quel momento.
In materia di agenzia esiste un precedente che potrebbe sembrare di segno opposto. Il Tribunal Supremo ha impedito alle parti di suddividere l’indennità per periodi mediante successive dichiarazioni di «nulla a pretendere» (sentenza del 27 giugno 2013). La ragione, però, era il carattere inderogabile della tutela prevista dall’articolo 28 della legge spagnola sul contratto di agenzia, che le parti non possono escludere. Questo limite non opera nella distribuzione.
Anche se la rinuncia fosse rimasta efficace, resterebbe la questione del preavviso. Il risarcimento per non aver concesso un termine sufficiente riguarda un danno diverso: compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività. Non sarebbe quindi necessariamente coperto da quella rinuncia.
Cosa dovrebbero fare i produttori che distribuiscono in Spagna?
Le imprese possono continuare a lavorare normalmente senza accorgersi che il contratto è scaduto. Questa sentenza mostra il rischio: quando arriva il momento di porre fine al rapporto, il produttore può scoprire che le tutele sulle quali contava non sono più efficaci.
È opportuno rinnovare il contratto per iscritto prima della scadenza. Se le parti hanno già continuato a lavorare senza rinnovarlo, dovrebbero documentare quali condizioni restano applicabili e prevedere espressamente che le rinunce mantengano i propri effetti sia dopo la scadenza sia durante la prosecuzione del rapporto senza un nuovo documento.
È importante anche precisare quale clientela rientri nella rinuncia. Se si intende includere quella già sviluppata, occorre dirlo espressamente, indicando una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Infine, l’indennità di clientela, il risarcimento per insufficiente preavviso e gli altri danni devono essere disciplinati separatamente. Quando pone fine al rapporto, il produttore deve concedere un preavviso proporzionato alla sua durata.
Domande frequenti sull’indennità di clientela in Spagna
La rinuncia all’indennità di clientela è valida in un contratto di distribuzione in Spagna?
In linea di principio sì: nella distribuzione il distributore può rinunciare all’indennità, mentre nell’agenzia la legge tutela l’agente contro una rinuncia anticipata (articolo 3 della legge spagnola 12/1992). La rinuncia offre però meno certezze se il produttore pone fine al rapporto senza giusta causa e con un preavviso insufficiente.
Cosa succede alla rinuncia se il contratto scade e le parti continuano a lavorare?
Il rischio è che non venga applicata. Nel caso deciso dall’Audiencia Provincial di Barcellona la rinuncia è stata ritenuta non più efficace perché il contratto era scaduto e le parti avevano continuato a lavorare senza rinnovarlo. L’argomento è discutibile, ma per evitare l’incertezza conviene rinnovare il contratto per iscritto o prevedere espressamente che le rinunce mantengano i loro effetti.
La buona fede può limitare una rinuncia all’indennità di clientela?
Secondo la Corte, in quel caso sì: dopo oltre venticinque anni di collaborazione, con una clientela sviluppata dal distributore e una cessazione senza giusta causa, la rinuncia non avrebbe potuto produrre pienamente i suoi effetti.
La rinuncia copre anche il risarcimento per insufficiente preavviso?
Non necessariamente. Il risarcimento per il preavviso riguarda un danno diverso, perché compensa il distributore per non aver avuto un tempo ragionevole per riorganizzare la propria attività.
Come va formulata la rinuncia per coprire la clientela già sviluppata?
Va detto espressamente: occorre indicare una data di riferimento, un territorio e il carattere definitivo della rinuncia.
Quanto preavviso deve dare il produttore?
L’articolo non indica un numero di giorni: dice che il preavviso deve essere proporzionato alla durata del rapporto. Nel caso esaminato il produttore aveva concesso meno di due mesi dopo oltre venticinque anni di collaborazione.
A European manufacturer supplies a critical component to a New York-based distributor. Shortly after delivery, questions emerge about whether the product complies with U.S. safety requirements. The distributor pauses shipments while the issue is reviewed.
Customers want to know when orders will resume. Sales teams are fielding questions. A trade publication calls for comment. Regulators want information.
The distributor tells customers that shipments have been paused while the issue is investigated. The manufacturer believes that explanation is incomplete and may leave customers with the impression that the product is unsafe or that the manufacturer caused the problem.
The contract is detailed. It says what happens if a party defaults, who can terminate and where a dispute will be heard. It also deals with confidentiality and public disclosure. What it does not say is how the parties should communicate when the problem becomes public and both need to respond.
The legal position may still be unclear. The facts may still be coming together. But someone has to answer the customer asking why a shipment has not arrived or the journalist seeking comment.
And what one party says can quickly become the other party’s problem.
Publicity clauses only take you so far
Most international agreements already deal with confidentiality and public announcements. Some commercial contracts may restrict the use of a counterparty’s name or the disclosure of information about the relationship.
Those provisions usually focus on consent and disclosure. They are less useful when both parties need to respond to the same event at the same time.
The communication that causes trouble may not be a press release at all. It could be a customer email saying, “Our supplier has failed to deliver.” It could be a technology company telling users that an outage originated in its client’s systems.
The sender may see the wording as factual. The other side may see blame being shifted.
By the time lawyers are debating whether the statement breached the agreement, customers may already have formed their own conclusions.
Cross-border relationships make coordination harder
Time zones are the obvious example.
Suppose the problem comes to light in New York after the European working day has ended. Customers want an answer. Reporters are calling. The people who would normally approve a statement are in Paris, Frankfurt or Milan and cannot be reached.
A requirement for prior consent to every external statement may look sensible on paper. In practice, it may be impossible to follow.
Some of these practical issues can be settled in advance. The contract can identify the types of events that require consultation, the right contacts on each side and expected response times. It can also say what happens if one side cannot be reached, including whether the other may issue a holding statement.
The clause can be short. Consultation, advance notice where practicable and enough information-sharing to keep communications accurate may be all that is needed.
The contract does not need to become a crisis plan. It just needs to give the parties a process they can use when the problem is already unfolding.
One party may also have to speak before the other is ready. A public company may face a disclosure deadline even while its commercial partner is still investigating the facts.
In the United States, for example, a public company generally has four business days after determining that a cybersecurity incident is material to file the required disclosure on Form 8-K. In that situation, consultation and advance notice where possible usually make more sense than giving either party an absolute veto.
When the stories start to diverge
The bigger challenge is when the two sides no longer agree on what happened.
One party may think the other is giving customers an inaccurate account and want to correct it. It may want to contact shared customers directly. The other party may see that as an escalation.
The same issue can continue after termination. Each party may want to reassure customers and employees and explain why the relationship ended. Their accounts may not match.
If the parties want consultation requirements or restrictions on naming one another to continue after termination, the contract should say so.
Keep it practical
There are limits to what a communications clause can do.
It cannot override a legal disclosure obligation. It cannot make two companies agree on disputed facts. It should not require either side to disclose privileged or otherwise protected information, or give one party an open-ended right to stop the other from speaking.
Commercial contracts are usually very detailed about what happens if the relationship breaks down. They specify who can terminate, what remedies are available, where disputes will be heard and which law applies.
They are often less useful once the problem becomes public and people outside the contract want answers.
By then, what each side says may be affecting the commercial relationship as much as the dispute itself. Agreeing in advance on who needs to be consulted and what happens when time is short can prevent the communications problem from becoming another dispute.
Imagine you are the CFO of a multinational group. You receive an urgent WhatsApp message from your CEO:
“We’re closing an acquisition in Portugal. I need you to transfer 850,000 EUR to this account immediately. It’s confidential and urgent.”
The pressure feels real. The profile picture matches. The context sounds plausible.
Or imagine a long‑standing foreign supplier suddenly “updates” the IBAN for the payment of a recent order. The email arrives inside an existing email thread about that very supply. Same document style, same signatures, same tone. Everything looks normal.
The next day, you discover the CEO never sent that message – and the supplier never changed bank details. Your company’s funds have been transferred to a Portuguese bank account controlled by fraudsters.
These scenarios are not hypothetical. In recent years, Portuguese authorities have dismantled networks that diverted millions of euros through these methods, often using Portugal as a transit jurisdiction to receive and rapidly dissipate fraudulent proceeds.
What is CEO Fraud (BEC) and how does “money mulling” work?
CEO Fraud is part of a broader family of schemes commonly referred to as Business Email Compromise (BEC), invoice fraud, or CEO impersonation. The objective is simple: induce a company to make a payment to an account controlled by criminals by exploiting trust, urgency, confidentiality, and internal processes.
The tactics have evolved well beyond crude spoofed emails. Today, fraudsters frequently use:
- Messaging apps (WhatsApp, Telegram, Signal) to impersonate senior executives;
- Compromised email accounts (real inbox access) to insert themselves into legitimate conversations;
- Typosquatting (look‑alike domains), e.g. companybeta.com vs companybetas.com;
- Payment diversion at the last minute (“new bank account details”, “audit reason”, “confidential deal”, etc.).
Once funds are transferred, they are typically routed through money mules (or “money mulling” schemes): individuals (often young or in financial distress) who allow their bank accounts to be used to receive and quickly forward funds. The most common method is doing this operation scheme through newly incorporated companies whose accounts are used as temporary “pass‑through” vehicles.
In many cases, the money mule is the only identifiable link when the fraud is detected, while the organisers remain behind layers of transfers and cross‑border complexity.
Why immediate action matters: the first 48–72 hours
Speed is a decisive factor in the recovery of assets. The first 48 to 72 hours are often critical to prevent funds from being fragmented across multiple accounts, moved abroad, or converted into cryptoassets.
Even if that immediate reaction does not occur, companies should act as quickly as possible. A coordinated response is typically required across multiple jurisdictions (e.g., where the company is based, where the recipient account is located, and where subsequent transfers may have gone). This coordination helps ensure urgent engagement with the banks involved (payer bank and recipient bank), payment service providers, and the relevant judicial authorities.
The goal is to preserve evidence, obtain timely information, and pursue measures that may prevent dissipation of funds.
Criminal investigation in Portugal: effective tools, practical limitations
CEO Fraud schemes typically involve conduct that may qualify (depending on the factual pattern) as offences such as computer fraud, money laundering and criminal association.
Portuguese criminal procedure provides mechanisms that can be effective in these cases, including measures that may lead to freezing the movement of funds and seizing amounts held in bank accounts.
In practice, however, the pace of criminal investigations does not always match the operational speed of fraud networks. These cases are usually handled under judicial secrecy, follow their own procedural rhythm, and may require international cooperation to track transfers and identify the individuals behind the scheme.
For victim companies, this can mean long periods without meaningful updates – a reality that often generates understandable frustration and prompts consideration of alternative or parallel strategies.
Civil alternatives: information gathering and precautionary freezing measures
A route that is often overlooked in the initial crisis — but can be valuable — is the civil strategy.
Depending on the circumstances, civil proceedings (including precautionary measures) may help a victim company:
- obtain relevant information regarding the recipient account(s) and transaction flows (subject to judicial assessment and proportionality), and/or
- seek preventive freezing of available balances.
This approach is case‑specific and must be assessed urgently. When viable, it can play an important role in bridging information gaps and acting before funds are dissipated.
Can the recipient bank be liable? Traditional stance and a changing landscape
When fraudulent funds are received into Portuguese bank accounts — especially accounts opened by newly created companies, followed by rapid high‑value outgoing transfers — questions often arise about the role of the recipient bank.
Historically, Portuguese courts have tended to take a restrictive approach to the civil liability of recipient banks, particularly where the payer provided the correct IBAN (even if under deception). In addition, breaches of anti‑money laundering (AML) obligations have often been treated primarily as matters of regulatory, administrative or criminal enforcement, rather than as a straightforward basis for civil liability towards third parties.
That said, each case should be assessed on its own facts, including what was knowable and observable by the recipient bank, the transaction pattern, the customer profile, the timing, and the specific compliance obligations at play.
For additional perspectives within the Legalmondo network, see the Spanish analysis on Man‑in‑the‑Middle fraud and bank liability and the Italian perspective on CEO fraud in international groups.
Verification of Payee (VoP): a major compliance and fraud‑prevention shift in Europe
Against this background, the regulatory environment is evolving.
Regulation (EU) 2024/886 (the “Instant Payments Regulation”) strengthens the framework for euro credit transfers and introduces, among other measures, the obligation for payment service providers to offer a Verification of Payee (VoP) service. In short, before a transfer is authorised, the payer should be informed whether the beneficiary name matches the IBAN (or whether there is a close match/no match), helping reduce misdirected payments and social‑engineering fraud.
In Portugal, the Central Bank (Banco de Portugal) has indicated that its VoP service is available from 5 October 2025, and EU‑level implementation deadlines for banks in the euro area are tied to October 2025 obligations under the Regulation.
For corporate finance teams, VoP will not eliminate CEO Fraud (criminals adapt quickly) but it adds a meaningful friction point that can prevent (or at least flag) certain payment diversions.
Practical checklist: what companies should do immediately after discovering CEO Fraud
- Stop and document: Preserve emails (including headers), chat logs, attachments, invoices, and internal approvals.
- Notify banks urgently: Contact both the payer bank and the recipient bank; request immediate action to trace/freeze funds where possible.
- Escalate internally: Finance, legal, IT/security, and management should coordinate a single incident response.
- Engage counsel across jurisdictions: Parallel steps may be needed in the jurisdictions involved.
- Consider criminal and civil paths: Criminal complaint and cooperation with authorities; assess civil/precautionary measures for speed and information.
- Contain the breach: If email compromise is suspected, secure accounts, reset credentials, review forwarding rules, and harden Multi-factor authentication (MFA).
Conclusion
CEO Fraud (BEC) is a fast‑moving threat that exploits corporate trust and payment workflows. When Portugal is part of the payment chain (whether as recipient jurisdiction or as a transit route) a successful response depends on speed, cross‑border coordination, and a clear strategy combining criminal and, where appropriate, civil measures.
At the same time, regulatory developments such as Verification of Payee under Regulation (EU) 2024/886 signal a new European focus on preventing misdirected payments — an important step, particularly for corporates exposed to high‑value cross‑border transfers.
Foreign franchisors entering into franchise agreements in Spain should take careful note of the content of the judgment issued by the Provincial Court of Córdoba on November 20, 2025, and require that the partner(s) and the directors of the franchisee company expressly guarantee and indemnify the payment of any debts arising from the franchise agreement.
Spanish corporate law establishes the principle of liability for the directors of corporations or limited liability companies when the company is subject to dissolution (for example, due to losses that reduce equity to less than 50% of the share capital) and, despite this, they fail to convene a meeting to adopt corrective measures (dissolution or capital increase).
In the case of the aforementioned ruling, the franchisor was unable to collect the debt arising from the franchise agreement from the franchisee due to the latter’s insolvency; so it decided to claim that debt from the company’s administrator based on the provision mentioned above, that is, due to the fact that the franchisee company was facing dissolution due to losses and the administrator had not convened a shareholders’ meeting, as was his obligation, so that the shareholders could decide how to resolve the situation.
The ruling we are discussing from the Court of Appeal of Córdoba upholds the lower court’s decision and dismisses the franchisor’s claim against the sole administrator of the franchisee company, stating that:
With regard to liability for corporate debts under Article 367 of the Capital Companies Act, the court recognised the existence of the corporate debts, the presence of grounds for dissolution, the breach of the legal obligations by the corporate administrator, and his liability, but found that a ground for exoneration from liability existed in accordance with the doctrine of “known risk.” Thus, it was noted that the plaintiff is a franchisor and X. S.L. was the franchisee, and it was evident from the electronic communications that the franchisee was under constant monitoring and the franchisor was aware of the risk involved in the operations, halting the shipment of goods (clothing) as soon as the limits of the guarantees granted were exceeded, meaning the plaintiff voluntarily assumed the risk. For all these reasons, the claim was dismissed.
In conclusion, and in light of the foregoing, the present franchise relationship and its conduct allow us to consider that it has been established that the franchisor (creditor) had greater knowledge of the franchisee’s (debtor’s) financial situation, beyond the information appearing in the annual accounts filed with the Commercial Registry, as it was the franchisee’s primary supplier. And this knowledge and control of the debt by the franchisor (through the increase in orders) justifies the exoneration of the corporate director’s liability for corporate debts under Article 367 of the Capital Companies Act, which leads to the dismissal of the appeal
The legal theory or principle of Known/Accepted Risk, to which the judgment refers, holds that harm caused to a third party, with or without a contractual relationship in place, is not considered unlawful if the victim was aware of the risk and voluntarily assumed it.
This doctrine was initially developed within the framework of tort liability: whoever engages in a risky activity and reaps its benefits must bear its negative consequences, that is, the risk—(cuius commodum, eius incommodum).
However, case law has extended the application of this theory to the field of contractual liability, as demonstrated in the judgment under discussion.
Therefore, since the plaintiff was aware of the defendant’s financial situation and solvency—having “monitored” its activity as a franchisor—and despite this, decided to maintain the contract’s validity, thereby increasing the debt, the ruling holds that the franchisor assumed the risk, which constituted grounds for exonerating the administrator from liability. However, more concerning than the above is that this “known risk” theory could be considered applicable to the liability of the franchisee company itself, which could be exonerated from liability based on the franchisor’s monitoring of its activities.
The conclusion of all the above is that, based on this application of the known risk theory, franchisors may face difficulties in claiming debts owed by the franchisee company from its directors in the event of the company’s insolvency; therefore, it is highly advisable that, when signing the franchise agreement, a joint and several guarantee for the franchise’s potential future debts be required from its directors and partners, which, moreover, is a fairly standard practice.
In this way, the objection based on the theory of known risk would not come into play.
Trust is the only thing a law firm sells.
It takes years to build a reputation and minutes to damage it. In a crisis, that reality becomes visible. Client calls increase. Internal questions surface. Reporters start asking questions. Recruiters take note.
What begins as an individual lapse, a client controversy, or an internal weakness quickly becomes a communications test. How leadership responds, who speaks, and how consistently the message is delivered will determine how the firm is judged.
Crisis management in a law firm is not primarily a legal problem. It is a leadership problem, expressed through communication.
The Added Complexity Facing Modern Firms
Legal practice is more exposed than it was even a decade ago. Firms operate across jurisdictions and serve sophisticated clients. Expectations about transparency and accountability are not the same everywhere. What sounds careful in one jurisdiction can sound evasive in another.
When something goes wrong, reactions do not stay local. Clients, regulators, employees, and the media may all respond at the same time, often in different markets. If offices or practice groups answer differently, confusion grows and scrutiny increases.
Staying silent rarely helps. If the firm does not explain what is happening, it loses control of the narrative.
Where Law Firm Crises Begin
Most law firm crises originate in one of three areas:
- Individual behaviour
- Client-related risk
- Systemic issues within the firm itself
Individual misconduct is usually the most visible.
Widely reported cases in recent years involving senior partners at major firms have followed a familiar pattern. An incident at a firm event is initially treated as isolated. Leadership hesitates, weighing relationships and reputational risk. Within weeks, the issue moves beyond the room. Focus shifts from the conduct itself to how the firm responded. What began as a behavioural issue becomes a test of leadership judgment.
Hesitation changes the narrative. Once that shift occurs, the firm is no longer addressing behaviour. It is defending its decision not to act.
Technology has created a different kind of exposure. Several firms have faced scrutiny after courts or opposing counsel identified AI-generated citations that did not exist. Internally, the explanation was familiar. A junior lawyer relied on a tool. Supervision was assumed rather than confirmed. Externally, those details mattered far less than the perception that basic controls had failed.
The communications challenge is not explaining how the error occurred. It is addressing the confidence gap that follows. Courts and clients do not reward technical explanations when oversight appears weak.
Client-related crises are often the most difficult to navigate publicly.
Firms may believe that engagement letters create a buffer between client and firm. In practice, when a client becomes controversial, that distance collapses. Media coverage rarely distinguishes between legal advice and endorsement. Once the firm’s name appears in the same headline, it becomes part of the story.
Communications strategy must reflect the fact that clients, regulators, employees, and journalists will interpret the situation through different lenses. A single message rarely satisfies all of them.
Systemic and cultural issues present a different communications risk.
Pay disparities, unclear promotion criteria, tolerance of poor behaviour, or weak reporting channels often develop over time. When lawyers leave and speak openly about their experiences, internal issues become external narratives. Culture becomes part of the firm’s public identity.
What a firm can say credibly in a crisis depends on what it has done consistently before one. Reputation limits the range of believable responses.
* * *
Where Law Firm Crisis Communications Often Falters
Lawyers are trained to be careful and precise. That is usually a strength. However, in a crisis, it can backfire. Statements may be technically accurate, but they leave obvious questions unanswered.
The pattern is familiar. A carefully worded statement is released. Reporters and clients focus on what was not said. Follow-up questions arrive. Another clarification is issued. Each round keeps the story alive. What felt prudent inside the firm can look like hesitation from the outside.
Mixed messaging makes things worse. Different partners speak to different audiences. Offices respond on their own. Legal advice and communications advice are not aligned. The result is inconsistency, and inconsistency weakens credibility.
In a reputational crisis, people form views quickly. Once confidence slips, it is hard to rebuild.
What Effective Law Firm Crisis Communications Looks Like
Effective crisis communications is disciplined and coordinated. It begins with a clear understanding of what is known, what is not known, and what can responsibly be said. Acknowledging facts early, without speculation, builds credibility. Overstatement creates risk. Evasion creates suspicion.
Decisions reinforce messages. Policy changes, leadership actions, or the appointment of an independent investigator often carry more weight than carefully chosen language.
Structure matters. One spokesperson. Clear internal guidance. Alignment between leadership, legal counsel, and communications advisors. Without that alignment, even strong decisions can appear uncertain.
Above all, the institution must come first. Communications strategies that appear designed to protect a single individual at the expense of the firm tend to fail. That risk is greatest when senior figures are involved. Allegations concerning senior partners attract heightened scrutiny and test whether the firm’s standards apply consistently or only when convenient.
Externally, the focus should remain on process and oversight rather than contested detail. Internally, communication must reduce speculation while respecting confidentiality. The objective is to demonstrate that the firm’s standards apply consistently.
Anything less invites doubt.
Crisis as a Communications Test
Every crisis ultimately becomes a communications test.
The underlying issue matters. So does how leadership responds, how consistently it speaks, and whether actions align with words.
Firms that respond with clarity, fairness, and coordination are more likely to preserve trust, even in serious situations. Firms that respond slowly or unevenly often extend the story and deepen reputational harm.
Crisis communications is not about spin. It is about protecting credibility when it is under pressure. And for law firms, that credibility is the business.
Summary: The challenge with preventive legal work is that it’s difficult to justify in the corporate budget—especially in organizations lacking a strong culture of risk prevention and mitigation. This article offers a practical solution: applying a “value-at-risk” approach helps leadership understand why every euro spent on preventive legal assessment can prevent multiple euros in litigation costs, sanctions, business disruption, and avoidable losses. A simple Return on Legal (ROL) metric makes that value tangible by calculating avoided costs from past disputes and modeling the financial effects of potential future lawsuits.
Why Legal Risk Management Needs a Financial Metric
Most companies already invest in preparedness—just not consistently in legal. They run security drills, insure assets, addres civil and product liability, test business continuity plans, and model financial risk. However, legal risk is often overlooked and, when considered, remains in the “qualitative” bucket: high/medium/low, red/amber/green, or a list of concerns in a memo.
That becomes a problem when decisions are made. Budgets are approved in numbers, not adjectives. If companies want legal preparedness to be funded like business preparedness, they need a framework that decision-makers are already familiar with. That’s where applying a value-at-risk approach helps.
Legal Risk as Value-at-Risk
Value-at-Risk in finance asks a simple question: how severe could the downside be, and how often might it happen? Legal risk can be approached in a similar way by considering two factors: the likelihood of an event (such as a claim, dispute, investigation, enforcement action, fine, lawsuit, or class action) and the impact if it occurs. Things can get very complicated, but for the sake of this article, a very simplified way to express it for a single- well defined, loss event might be:
“Total impact” is often underestimated when assessing legal risk. Direct legal costs are just one part of the picture. A dispute can consume leadership time, divert key teams from revenue-generating work, slow down delivery or product launches, damage supplier relationships, and cause customer hesitation. In other words, legal risk is often an operational risk with legal triggers.
Therefore, we should consider that legal risk rarely appears as a “fixed impact if it happens,” and the expected risk value often accumulates through the correlation of different factors. For example, one investigation can trigger follow-on lawsuits, a license can be revoked, a class-action can start, or enforcement can occur across multiple jurisdictions. If we want to account for this scenario (“how severe could the downside be and how frequently”), then the framework should involve a loss distribution over a period, which might look like this.
Expected legal loss (per period) = expected frequency x expected severity
This isn’t about finding the perfect formula. It’s about making legal exposure comparable to other risk areas where investment decisions are routinely supported with quantified downside.
Introducing Return on Legal (ROL)
Preventive legal work often goes unnoticed when it succeeds. When a contract dispute is avoided or a claim is settled early, there is no dramatic event—only the absence of damage. This is exactly why preventive advisory is often seen as a cost during budgeting: it appears more like an expense than an investment. A Return on Legal (ROL) metric addresses that gap by translating prevention into business results. In practical terms, ROL shows how much cost and disruption you save for every euro/dollar invested in legal risk assessment and prevention.
A definition could be expressed as follows:
When considering avoided losses, one should factor in a projection over a period of time (e.g., 3 years), the probability of a claim (e.g., 10%), and a baseline frequency of disputes. From there, it’s easy to get lost in complex calculations that take many variables into account; my point is not to achieve perfect precision but to make a credible, quantifiable estimate that supports better decisions in legal risk assessment and budgeting.
Measuring ROL: Retrospective vs. Forward-Looking
A convincing ROL approach combines what companies already know from experience with what can reasonably be modeled going forward.
First, there is the backward-looking perspective: assessing costs based on past litigation and disputes. Most companies have at least a few cases that can serve as reference points. The task is to identify where earlier legal intervention could have minimized the likelihood of escalation or the severity once a matter arose. This could be something as simple as improved clauses that prevent a dispute from escalating, earlier involvement of external counsel leading to quicker settlements on better terms, or custom dispute resolution clauses that reduce discovery burdens and strengthen the negotiating position.
To estimate backward-looking ROL without overclaiming, we can set a baseline for “what happened” or what usually occurs when that type of risk materializes without intervention. Then, compare that baseline with the results achievable when preventive measures are in place. There’s no need to pretend we can calculate the exact euro value to the last cent. What we require is a defensible range, based on actual costs (fees, settlement amounts, internal time) and business impacts that can be reasonably estimated (delayed launches, downtime, diverted capacity).
Second, there is the forward-looking perspective: forecasting the financial impact of potential future lawsuits. This is where the value-at-risk approach proves powerful. Decision makers identify the most relevant exposure types for their business and develop scenarios for each—typically best case, base case, and worst case—then assign probability ranges. The simulation becomes more meaningful when they consider how specific preventive measures influence the model. Some actions decrease probability (for example, compliance controls and training). Others lessen impact (such as better contracts, liability limitation clauses, response protocols).
Many do both. In the end, leadership gets a quantified story: this prevention program lowers expected annual legal losses and reduces exposure to litigation-related damages. This mirrors the decision-making approach used in other preparedness and risk-management programs.
Let’s make an example of how ROL works
Imagine a business line where disputes often come from contract ambiguity and inconsistent negotiation practices. In the past, the company occasionally faced lawsuits or arbitration, but more frequently it dealt with costly “pre-litigation” escalations that still took months and used up a lot of internal resources.
A preventive program—featuring updated templates, negotiation playbooks, and targeted training—incurs a clear cost. From a value-at-risk perspective, you compare that expense to the expected loss without the program over a certain period: not only external fees and settlements but also the estimated operational impact of ongoing disputes. If the program decreases how often disputes escalate and accelerates resolution times, the avoided losses can quickly outweigh the preventive costs. That difference reflects what ROL captures in a way that leadership can act on.
ROL Implementation: Keep It Lean and Actionable
ROL does not require a perfect dataset on day one. What it needs is consistent categorization, conservative assumptions, and a commitment to improve the model over time. A practical starting point is to gather three streams of information: historical disputes and their total costs; recurring risk hotspots (such as contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, client disputes); and operational impact estimates that the business already uses in other contexts (like cost per hour of downtime, cost of delays, internal resource allocation).
A practical starting point is to pull together three streams of information:
- historical disputes and their total cost;
- recurring risk hotspots (contracting patterns, product or market launches, HR issues, data/privacy exposure, supplier disputes, clients disputes); and
- operational impact estimates that the business already uses in other contexts (cost per hour of downtime, cost of delays, internal resource allocation).
Where data is uncertain, ranges can be helpful. Managers can assign confidence levels and keep the model honest by using conservative estimates. Over time, the ROL model becomes more accurate as the company consistently tracks legal events and as prevention initiatives develop. The most important mindset shift is to treat legal as you would other risk functions: as a measurable way to minimize downside, not just a reactive cost center.
Turning ROL Into a Decision Tool
Once legal risk exposure can be expressed in value-at-risk terms, companies can prioritize legal work using the same logic as other investments: risk reduction per euro spent. This shifts the conversation from “Should we spend on prevention?” to “Where do we get the biggest reduction in expected loss and tail risk?” ROL also improves alignment with business teams. Instead of speaking in purely legal categories, it is possible to connect legal work to operational outcomes—fewer delays, fewer escalations, faster resolution, reduced management distraction, greater predictability in commercial relationships. Over time, this fosters a healthier operating rhythm: legal risk reviews transition from being ad hoc to becoming a routine part of preparedness, similar to finance risk reviews or security protocols assessments.
Conclusion
Applying a value-at-risk perspective to preparedness reveals legal risk in the language corporate leadership already uses to allocate resources. A Return on Legal (ROL) metric then makes preventive legal advice concrete by turning avoided costs and operational losses into measurable value. By combining evidence from past disputes with future-focused simulations of potential lawsuits, companies can build a credible, data-driven argument that every euro invested in legal risk assessment can prevent multiple euros in losses—and that prevention is not just a “nice to have,” but a vital part of operational resilience.
Quando un’azienda italiana decide di entrare sul mercato statunitense, spesso sottovaluta uno degli aspetti più critici e costosi del fare business oltreoceano: il sistema giuridico statunitense. Non si tratta semplicemente di una questione linguistica o di differenze culturali superficiali, ma di un intero ecosistema giuridico che opera secondo logiche profondamente diverse rispetto a quelle italiane ed europee. Comprendere queste differenze non è un dettaglio tecnico da delegare ai legali, ma una questione strategica che può determinare il successo o il fallimento di un’impresa sul mercato statunitense.
Ho avuto il piacere di curare l’edizione italiana del libro di un collega di Legalmondo, l’avvocato californiano, esperto di contenziosi, Kent Schmidt, che nella versione italiana è intitolata: Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti (qui su Amazon).
Il primo capitolo del libro spiega alcune importanti caratteristiche che rendono il sistema giudiziario americano un unicum nel panorama internazionale: è fondamentale conoscerle per operare in modo consapevole e sicuro negli Stati Uniti.
Le particolarità che trasformano il sistema legale USA in un campo minato
Il Sistema di Common Law
La prima grande differenza che un imprenditore italiano deve metabolizzare riguarda la natura stessa del diritto americano. Mentre in Italia e in gran parte d’Europa (con l’eccezione di UK e Irlanda) operiamo all’interno di un sistema di civil law, dove le leggi scritte e i codici rappresentano la fonte primaria del diritto, gli Stati Uniti hanno ereditato dal Regno Unito un sistema di Common Law. In questo contesto, i precedenti giurisprudenziali non sono semplici riferimenti interpretativi, ma hanno un valore vincolante che plasma continuamente l’evoluzione del diritto.
Questa caratteristica fondamentale crea un ambiente in cui la prevedibilità delle conseguenze legali dell’operato di un’impresa è molto più complessa rispetto a quello italiano. Una sentenza emessa da un tribunale può stabilire un principio che verrà applicato in migliaia di casi futuri, creando una rete di obblighi e responsabilità in costante evoluzione. Per un’azienda abituata alla stabilità del codice civile italiano, questa fluidità rappresenta una sfida significativa.
- Il primo riflesso pratico di questa differenza è la struttura dei contratti, che tendono ad essere molto più analitici e a riflettere le specificità del sistema USA: operare sulla base di un modello contrattuale standard, redatto su un modello di civil law, per questo motivo, può essere molto rischioso, perché spesso il testo non disciplina punti importanti, come la previsione di specifiche tutele e limitazioni di responsabilità, l’esclusione di certi tipi di danni, o la ripartizione dei costi legali in caso di contenzioso.
Spese legali altissime e compensi a tariffa oraria
Una seconda peculiarità del mondo legale USA è legata ai costi spesso astronomici di accesso alla giustizia. Gli avvocati sono generalmente remunerati con tariffa oraria ed è difficile pattuire un tetto massimo degli onorari, con il rischio che il costo finale dell’attività sia molto salato. Per dare una dimensione di grandezza, la tariffa oraria in studi legali di buon livello nelle principali città degli Stati Uniti si può aggirare tra 700 e i 1500 USD. La conseguenza è che, in caso di una vertenza giudiziaria negli USA, l’impatto dell’assistenza legale può – di per sé – costituire un costo straordinario di difficile gestione, specie per le imprese medio-piccole.
- Il consiglio pratico, a questo proposito, è di gestire con attenzione la clausola di scelta del foro competente nel contratto per evitare, se possibile (e corretto, nel caso di specie) di trovarsi convenuti davanti ad un giudice statunitense. È un argomento complesso, che va valutato con attenzione, avremo modo di approfondirlo in futuro.
Gli Accordi di Contingency Fee: quando l’Avvocato Diventa un Investitore nella causa
Una delle caratteristiche più sorprendenti del sistema americano per chi proviene dall’Italia riguarda il modo in cui gli avvocati vengono retribuiti. Nel nostro Paese, l’avvocato viene pagato per il suo tempo e le sue competenze, spesso secondo tariffe fisse, basate su tabelle ministeriali, che determinano l’onorario in base al valore della causa, indipendentemente dall’esito dell’azione giudiziaria. Negli Stati Uniti, invece, esiste una pratica diffusissima nota come “contingency fee”, che consente agli avvocati di essere pagati esclusivamente in caso di vittoria, trattenendo una percentuale del risarcimento ottenuto, tipicamente compresa tra il 25% e il 35%.
Questo meccanismo trasforma radicalmente gli incentivi del sistema legale. Un avvocato che lavora con questo modello diventa, essenzialmente, un investitore che scommette sul successo della causa. La conseguenza diretta è un aumento del tasso di litigiosità, che consente al cliente di minimizzare i costi fissi e all’avvocato di aumentare notevolmente il proprio guadagno in caso di vittoria della causa oppure (come accade spesso) di accordo transattivo favorevole al cliente.
Questo fenomeno alimenta ciò che in gergo si chiama “ambulance chasing“, letteralmente “caccia alle ambulanze”, un’espressione che descrive la pratica di alcuni studi legali di ricercare attivamente potenziali clienti che abbiano subito qualsiasi tipo di danno, anche minimo, per trasformarli in cause legali. Per un’azienda italiana che opera negli Stati Uniti, questo significa che anche un problema apparentemente banale o di routine, specie nel settore della vendita al consumo, può rapidamente trasformarsi in un contenzioso costoso e dispendioso.
- In questo caso, il profilo di rischio maggiore è legato alla presenza dei prodotti sul mercato, alla compliance con la normativa locale e ai messaggi pubblicitari: si tratta di un tema strettamente collegato a quello delle Class Actions, di cui parlo in seguito.
Il Processo con Giuria: dodici sconosciuti decidono il destino dell’azienda
Il Settimo Emendamento della Costituzione americana garantisce il diritto a un processo civile davanti a una giuria composta da dodici cittadini comuni in numerose tipologie di controversie. Questa è una bella differenza rispetto al sistema italiano, dove le cause sono decise da giudici professionisti.
Una giuria, infatti, è composta da persone senza alcuna formazione giuridica, che portano in aula i propri pregiudizi, le proprie esperienze personali e la propria visione del mondo. Quando un cittadino americano medio si trova a giudicare una controversia tra un consumatore locale e una società straniera, le dinamiche psicologiche che entrano in gioco possono essere complesse e imprevedibili. Non è raro che le giurie si lascino influenzare da storie emotive, da narrazioni che dipingono l’azienda come una corporazione senza volto che schiaccia il piccolo cittadino, o da pregiudizi nei confronti delle società straniere. Specie in quest’ultimo periodo, nel quale la politica americana tende a rappresentare una visione negativa e predatoria delle aziende straniere che esportano i prodotti negli USA.
Il rischio della cosiddetta “runaway jury“, la giuria fuori controllo, è una preoccupazione concreta per qualsiasi azienda che finisca in tribunale negli Stati Uniti. Si tratta di situazioni in cui i giurati, mossi da indignazione o empatia verso la parte lesa, possono assegnare risarcimenti sproporzionati rispetto al danno effettivamente subito. Anche se queste decisioni vengono spesso ridotte in appello, il processo può durare anni e costare (letteralmente) milioni di dollari in spese legali.
- Anche questo aspetto deve essere gestito all’interno della clausola di scelta delle modalità di risoluzione delle controversie: avremo modo di approfondirlo.
I Danni Punitivi: quando il risarcimento del danno diventa punizione esemplare
Nel sistema italiano, quando un tribunale riconosce che un’azienda ha causato un danno, il risarcimento viene calcolato per compensare la vittima della perdita effettivamente subita, tenendo in considerazione solamente i danni che sono conseguenza diretta e prevedibile dell’inadempimento contrattuale o del comportamento dannoso.
Negli Stati Uniti esiste invece l’istituto dei “punitive damages“, i danni punitivi, che rappresentano una somma aggiuntiva che il tribunale può imporre con finalità esplicitamente sanzionatoria e deterrente.
I danni punitivi non servono a compensare la vittima per ciò che ha perso, ma a punire l’azienda per il suo comportamento ritenuto particolarmente negligente, sconsiderato o doloso, e a dissuadere altre imprese dal comportarsi allo stesso modo. Le cifre possono essere astronomiche, raggiungendo talvolta multipli di dieci o venti volte l’ammontare del danno effettivo, arrivando a somme astronomiche.
Ciò che rende questo aspetto particolarmente insidioso per le imprese italiane è che, sebbene l’ordinamento italiano non riconosca l’istituto dei danni punitivi come contrario all’ordine pubblico, la Corte di Cassazione ha ammesso, in alcune circostanze, la possibilità di eseguire in Italia sentenze statunitensi che prevedono tali condanne. Questo significa che un’azienda italiana potrebbe dover pagare somme molto alte, stabilite da un tribunale americano, anche sul proprio patrimonio in Italia.
- La gestione di questo tema è possibile mediante l’inserimento di esclusioni e limitazioni di responsabilità in una specifica clausola del contratto.
Il Regime delle Spese Legali: una regola che fomenta la litigiosità
In Italia, come nella maggior parte dei Paesi europei, vige il principio secondo cui la parte soccombente in una causa deve rimborsare alla parte vincitrice le spese legali sostenute. Questo meccanismo funge da deterrente contro le cause infondate, perché chi decide di intraprendere un’azione legale sa che, se perde, dovrà pagare non solo il proprio avvocato ma anche quello dell’avversario.
Negli Stati Uniti funziona esattamente all’opposto. Secondo la cosiddetta “American Rule“, ciascuna parte paga il proprio avvocato indipendentemente dall’esito della controversia. Questo significa che un dipendente che decide di fare causa alla propria azienda per discriminazione, o un consumatore che lamenta un difetto del prodotto o una pubblicità ingannevole, possono intentare un’azione legale sapendo che, anche se perdono la causa, non dovranno rimborsare le spese legali dell’azienda, che possono ammontare a centinaia di migliaia di dollari.
Questo sistema crea un’asimmetria di rischio enorme a svantaggio delle aziende. Da un lato, il potenziale attore rischia poco o nulla, soprattutto se ha trovato un avvocato disposto a lavorare su base di contingency fee. Dall’altro lato, l’azienda convenuta in giudizio sa che, anche se vince, dovrà comunque sostenere ingentissimi costi legali. Questa dinamica incentiva fortemente le aziende a cercare accordi stragiudiziali anche quando a fronte di azioni giudiziarie temerarie, semplicemente perché difendersi costa troppo.
- Un accorgimento importante, a questo proposito, è quello di prevedere espressamente nel contratto che, tra i danni risarcibili in caso di inadempimento contrattuale, rientrino gli onorari dell’avvocato e le spese legate a un eventuale causa o arbitrato.
La Discovery: lo strumento processuale più invasivo e costoso del sistema americano
Chi non ha mai affrontato un processo negli Stati Uniti spesso non è preparato alla fase di “discovery“, che rappresenta probabilmente l’aspetto più costoso e invasivo dell’intero sistema legale americano. Prima che un processo arrivi effettivamente in aula, le parti hanno il diritto di ottenere dall’avversario una quantità pressoché illimitata di documenti, comunicazioni, e-mail, messaggi, registrazioni e qualsiasi altro materiale rilevante per la controversia.
Non si tratta di scambiare qualche documento come avviene in Italia. Le richieste di discovery in un caso mediamente complesso possono riguardare decine o centinaia di migliaia di e-mail, report interni, presentazioni aziendali, comunicazioni tra dipendenti, messaggi telefonici, e qualsiasi altra traccia documentale dell’attività d’impresa. Al fine di adempiere a questo obbligo l’azienda convenuta in giudizio deve dedicare un team dedicato, spesso con l’ausilio di costose società di consulenza legale specializzate in “e-discovery”, per setacciare i propri archivi digitali alla ricerca dei documenti richiesti.
La discovery, inoltre, non si limita ai documenti. Include anche le “deposizioni”, interrogatori sotto giuramento che gli avvocati della controparte possono condurre nei confronti di dipendenti, manager e dirigenti dell’azienda. Queste deposizioni possono durare giorni interi e rappresentano un’esperienza estremamente stressante per chi le subisce. Ogni parola pronunciata viene registrata e trascritta, e può essere usata successivamente in tribunale. Un’affermazione imprecisa o contraddittoria durante una deposizione può compromettere l’intera difesa dell’azienda.
Il costo della fase di discovery può facilmente superare il milione di dollari anche in controversie di medie dimensioni, e rappresenta una leva di pressione formidabile nelle mani degli studi legali che rappresentano gli attori. Molte aziende, dopo aver sostenuto mesi di discovery e visto lievitare le spese legali, decidono di trovare un accordo anche quando sono convinte di avere ragione, semplicemente perché continuare a difendersi diventa economicamente insostenibile.
Anche perché, nel frattempo, corre il tassametro delle spese legali degli avvocati che assistono l’impresa, come visto in precedenza, contribuendo alla rapida creazione di una montagna di costi legali.
- Se si opera sul mercato USA, è fondamentale conoscere questo procedimento e farsi trovare pronti, se necessario, ad adempiere alle attività necessarie, che richiedono una gestione ordinata e puntuale dei processi, delle informazioni e dei documenti legati all’operatività dell’azienda.
Le Class Action: migliaia di richieste confluiscono in una causa milionaria
Il sistema americano permette a gruppi di persone che hanno subito danni simili di unire le proprie richieste in un’unica causa collettiva, nota come “class action“. In teoria, questo meccanismo dovrebbe garantire efficienza processuale ed evitare di intasare i tribunali con migliaia di cause individuali identiche. Nella pratica, le norme particolarmente permissive che regolano le class action negli Stati Uniti hanno creato un’industria legale estremamente redditizia.
Gli avvocati specializzati in class action operano spesso come veri e propri “cacciatori di taglie”, alla ricerca di qualsiasi violazione potenziale che possa essere trasformata in una causa collettiva. Anche quando il danno individuale subito da ciascun membro della classe è minimo, magari pochi dollari, l’aggregazione di migliaia o milioni di richieste può trasformare la controversia in una causa dal valore di decine o centinaia di milioni di dollari.
Il sistema è incentivato dal meccanismo della contingency fee, visto sopra: il legale conclude con i partecipanti alla class action un accordo per il quale ha diritto a trattenere una buona parte del ricavato in caso di vittoria della causa o di accordo stragiudiziale.
Le aziende si trovano in una posizione di molto delicata di fronte alle class action. Il rischio di una sentenza sfavorevole può essere talmente devastante da mettere a repentaglio la sopravvivenza stessa dell’impresa. Anche quando l’azienda è convinta di non aver violato alcuna norma, la pressione a raggiungere un accordo stragiudiziale è enorme. Non è raro che le società preferiscano pagare decine di milioni di dollari per accordi transattivi piuttosto che rischiare il processo, contribuendo così ad alimentare ulteriormente questo circolo vizioso.
- Esiste un rischio di Class Action legato alla presenza di prodotti o servizi sul mercato statunitense? Come può essere prevenuto o mitigato? Alla domanda va data risposta confrontandosi con avvocati specializzati nel settore.
Orientarsi nel Labirinto Normativo
Se il sistema del contenzioso civile rappresenta la minaccia più visibile per le imprese straniere, il rischio normativo è forse quello più subdolo e pervasivo. Il codice federale degli Stati Uniti conta oggi oltre 60.000 pagine di normative, e questo è solo il livello federale. Ogni stato ha poi il proprio corpus di leggi e regolamenti, e all’interno degli stati ci sono contee e municipalità che aggiungono ulteriori strati di regolamentazione.
La California merita una menzione particolare in questo contesto. Lo stato più popoloso è anche quello con l’approccio più aggressivo alla regolamentazione delle attività economiche. Con oltre 200 agenzie di regolamentazione che producono un flusso costante di nuove norme, operare in California significa navigare in quella che è stata giustamente definita una “boscaglia normativa”. Ogni settore industriale ha le proprie regole specifiche, e spesso queste regole sono più stringenti rispetto a quelle federali.
Ciò che rende questo scenario particolarmente pericoloso è il duplice effetto che un’infrazione normativa può avere. Da un lato, la violazione di una normativa può far scattare sanzioni amministrative imposte dall’agenzia competente, con multe che possono essere estremamente salate. Dall’altro lato, la stessa violazione costituisce spesso il presupposto legale per una causa civile per danni promossa da privati cittadini o in forma di class action.
- In questo caso, la check-list delle attività di prevenzione del contenzioso prevede uno studio attento della normativa federale e statale applicabile al prodotto o servizio e un monitoraggio continuo di eventuali novità regolamentari o della giurisprudenza locale.
Conclusioni: navigare a vista può essere molto pericoloso
Le imprese italiane che vogliono avere successo negli Stati Uniti non possono permettersi di improvvisare o di sottovalutare la complessità del contesto legale. È fondamentale investire tempo e risorse nella comprensione approfondita dei rischi specifici del proprio settore, confrontandosi con professionisti legali competenti che guidino l’imprenditore nell’implementazione di sistemi di gestione del rischio corretti e aggiornati.
Ne parliamo in modo pratico nel libro Come Prevenire e Mitigare i Rischi di Contenzioso negli USA: Guida Pratica per le imprese italiane e i loro consulenti: se ti interessa la tematica, puoi acquistare il libro seguendo questo link.
For more than 35 years as a commercial lawyer, I have seen how many of us, myself included, confused effective advice with immediate and exhaustive answers. Now I feel that the worlds of law and business are changing: it is not enough to know (more and more laws, more requirements, more contradictory rulings… and more noise), but rather to listen, accompany and facilitate decisions. And that is where acting also as an executive coach offers an extraordinarily useful framework.
Lawyers are expected to solve problems. Executive coaches, however, help others (within an ethical framework) to discover the answer for themselves. And this can be a source of enormous professional and client satisfaction. When clients are faced with a problem, they do not need a legal analysis, but rather clarity and perspective to decide… based on ‘their problem’, not ‘our solution’. Integrating executive coaching tools into our professional practice transforms legal conversations and advice into something more effective: a decision-making process in which we accompany the client from start to finish.
I can think of three areas where the legal advisor and the executive coach meet:
- The relationship with the client. Listen carefully before advising.
Plutarch said that ‘listening well is the basis of living well’. And sometimes the client is not so much looking for an answer as for clarity in order to make a decision. Listening beyond what they say (and what they don’t say) allows us to understand what concerns them. A question can open up more avenues than a lecture, which will most likely leave them cold. When we listen without rushing and without bias, we create a space for reflection that helps clients to organise, prioritise and make meaningful decisions. Meaningful… for them.
- Negotiation and mediation.
In these processes, we use coaching techniques to help defuse resistance and move from confrontation to understanding. The lawyer-coach facilitates the parties listening to each other and discovering what lies behind their demands. A negotiation can be unblocked when the other party is allowed to express themselves. Agreements cease to be mere transactions and become shared decisions, which are more stable and sustainable over time and less likely to be sources of conflict.
- Accompanying processes of change in the client and their organisation
The lawyer-coach can become not only the drafter of the agreement but also the facilitator of change. They help those involved to understand what is at stake and align decisions with their values and objectives by managing resistance. The solicitor ceases to be a mere ‘provider’ of services (who is often only called upon at the end of the process) and becomes a partner in reflection.
In short, I perceive that today we are required to practise differently: less technical and more human, less reactive and more transformative. Coaching techniques help: conscious listening, constructive feedback, clarity of purpose… they allow us to better manage conflict, stress and uncertainty. Coaching, of course, does not replace the law, but rather broadens it and provides it with tools. Now, artificial intelligence (much faster and potentially much more comprehensive and exhaustive) is displacing us from our habits. Perhaps this allows us to glimpse that lawyers should not only be experts in rules, but also facilitators of difficult conversations, someone capable of combining analysis and empathy, precision and presence. Someone who understands that their value lies in helping their clients avoid conflicts or resolve them in the way that best suits them. And that is where the lawyer-coach has a lot to contribute.
Cartels, Compliance, and Data Privacy: The New “Brazil Risk”
- Compliance
- Privacy e Trattamento dati
-
Brasile
UE-Mercosur e il commercio del vino: cosa devono sapere gli avvocati prima dell’entrata in vigore dell’accordo
- Distribuzione
- Fisco e tasse
-
Brasile
 Tutte le categorie